Underwriter Resume Example (2026)
By FindAJobAI team Updated How we built this page
Underwriter ads, whether for mortgage, commercial lending or insurance, ask for the same backbone: reading financials or risk data accurately, applying guidelines consistently, and making sound decisions under volume. What sets candidates apart is evidence that their judgment held up, not just how many files they closed. An underwriter resume should name the loan or policy type, the decision and what it protected or enabled.
The example below is a mortgage underwriter with six years at a regional bank and a credit union. Each bullet names the file type, the volume and the result, such as a default rate or an approval turnaround, instead of counting files reviewed.
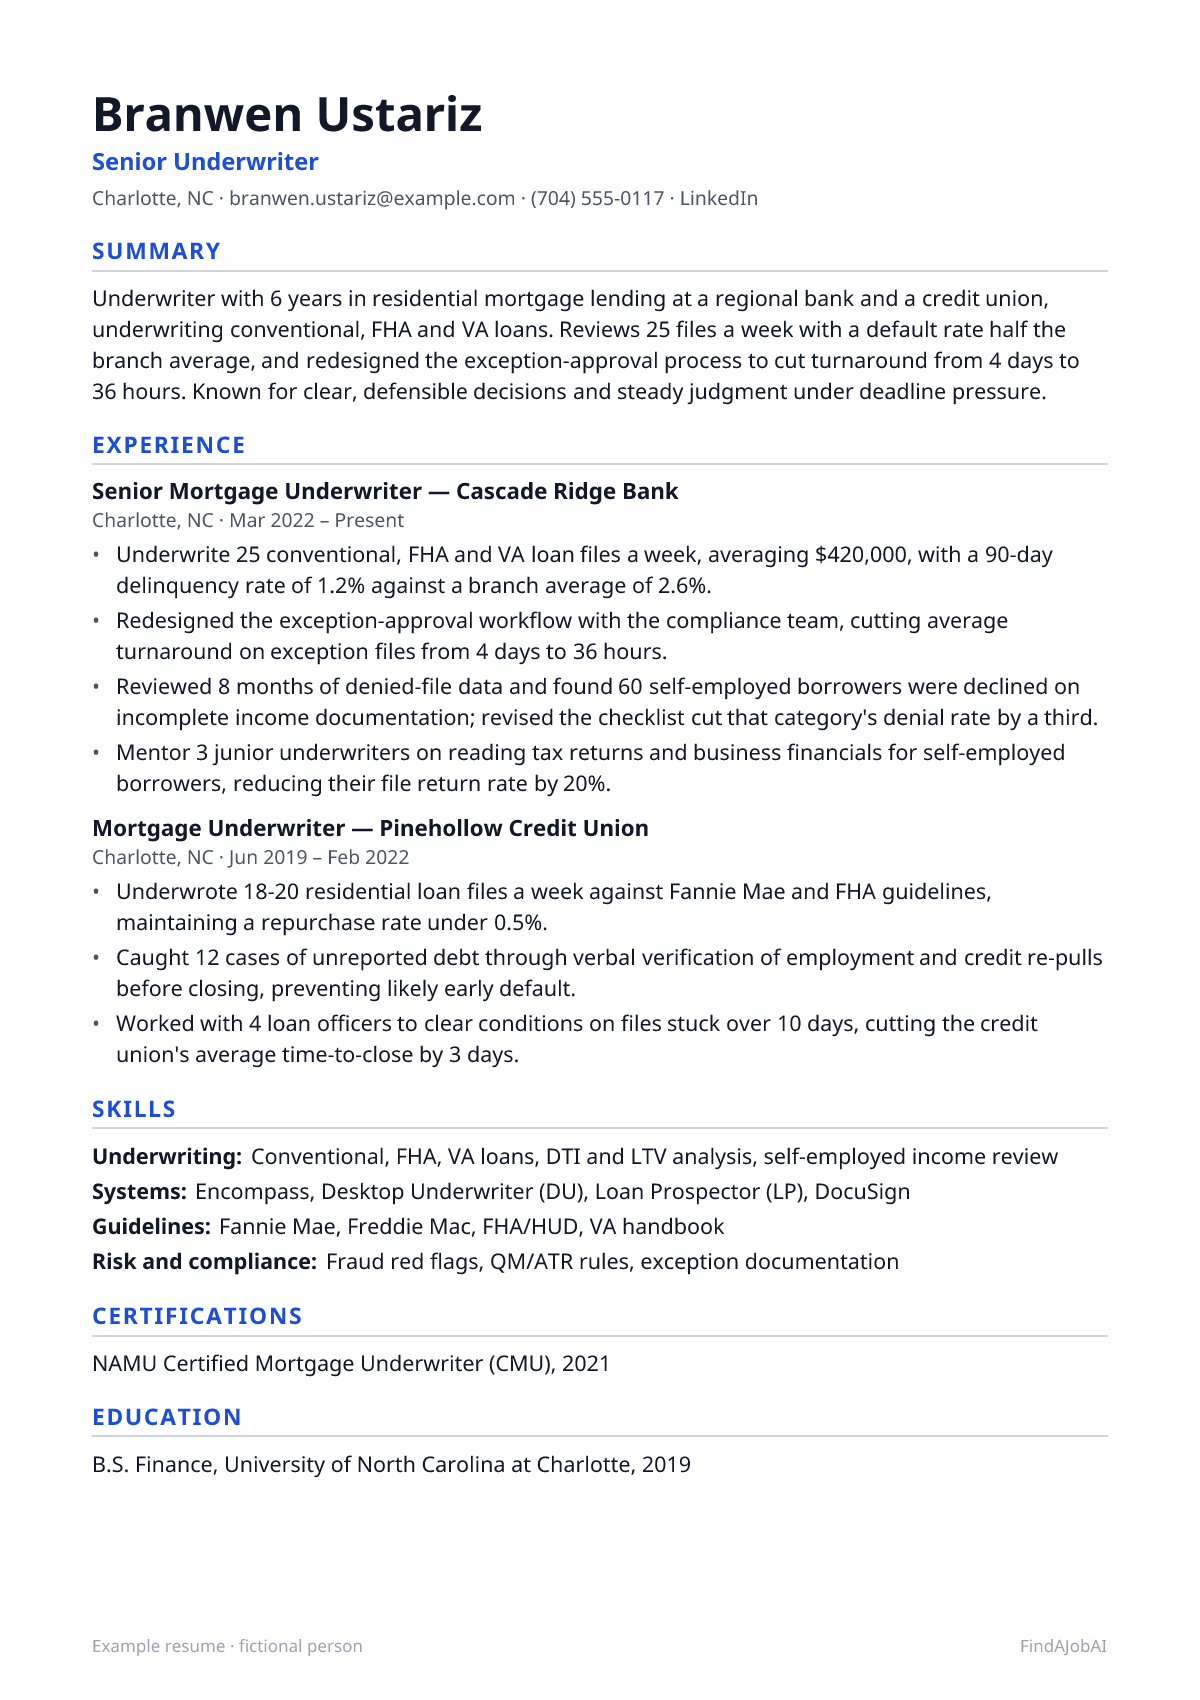
Underwriter resume template
This example as a one-page template: one column, standard headings and plain text, the format applicant tracking systems read most reliably.
After you sign up, Create my CV builds your own resume in this same one-column layout, from your real experience.
Mid-level underwriter resume example
A complete one-page example for a fictional underwriter: every bullet pairs an action with what changed because of it.
Example resume · fictional person
Summary
Underwriter with 6 years in residential mortgage lending at a regional bank and a credit union, underwriting conventional, FHA and VA loans. Reviews 25 files a week with a default rate half the branch average, and redesigned the exception-approval process to cut turnaround from 4 days to 36 hours. Known for clear, defensible decisions and steady judgment under deadline pressure.
Experience
Senior Mortgage Underwriter, Cascade Ridge Bank
Charlotte, NC · Mar 2022 – Present
- Underwrite 25 conventional, FHA and VA loan files a week, averaging $420,000, with a 90-day delinquency rate of 1.2% against a branch average of 2.6%.
- Redesigned the exception-approval workflow with the compliance team, cutting average turnaround on exception files from 4 days to 36 hours.
- Reviewed 8 months of denied-file data and found 60 self-employed borrowers were declined on incomplete income documentation; revised the checklist cut that category's denial rate by a third.
- Mentor 3 junior underwriters on reading tax returns and business financials for self-employed borrowers, reducing their file return rate by 20%.
Mortgage Underwriter, Pinehollow Credit Union
Charlotte, NC · Jun 2019 – Feb 2022
- Underwrote 18-20 residential loan files a week against Fannie Mae and FHA guidelines, maintaining a repurchase rate under 0.5%.
- Caught 12 cases of unreported debt through verbal verification of employment and credit re-pulls before closing, preventing likely early default.
- Worked with 4 loan officers to clear conditions on files stuck over 10 days, cutting the credit union's average time-to-close by 3 days.
Skills
- Underwriting: Conventional, FHA, VA loans, DTI and LTV analysis, self-employed income review
- Systems: Encompass, Desktop Underwriter (DU), Loan Prospector (LP), DocuSign
- Guidelines: Fannie Mae, Freddie Mac, FHA/HUD, VA handbook
- Risk and compliance: Fraud red flags, QM/ATR rules, exception documentation
Certifications
- NAMU Certified Mortgage Underwriter (CMU), 2021
Education
- B.S. Finance, University of North Carolina at Charlotte, 2019
Fictional example by the FindAJobAI team: the person, employers and numbers are invented. Keep the structure; use your own work and numbers you can explain in an interview.
Entry-level underwriter resume example
A finance graduate moving up from loan processing into underwriting, with a focused internship standing in for years of file volume. Education sits under the summary, and the bullets emphasize accuracy and guideline learning rather than independent decisions.
Entry-level example resume · fictional person
Summary
Entry-level underwriter with a B.S. in Finance and a loan processing internship at a regional bank, where he prepared files for underwriter review and shadowed decisions on 60 conventional loan files. Comfortable with Desktop Underwriter, credit report review and basic income documentation. Looking for a first underwriter role in residential mortgage lending.
Education
- B.S. Finance, Virginia Commonwealth University, 2026
Experience
Loan Processing Intern, Oakmere Regional Bank
Richmond, VA · Jan 2026 – May 2026
- Prepared 60 conventional loan files for underwriter review, verifying income documentation and credit reports against Fannie Mae checklists.
- Shadowed a senior underwriter on file decisions, taking notes on 2 denials that became training examples for new processors.
- Caught 8 files with missing or expired documentation before submission, cutting a recurring source of underwriter rework.
- Ran preliminary DTI and LTV calculations on 15 files a week in Excel, checked and corrected by the underwriting team.
Bank Teller, Oakmere Regional Bank
Richmond, VA · Jun 2024 – Dec 2025
- Processed an average of 50 customer transactions a day, balancing cash drawers with zero discrepancies over 18 months.
- Referred 20 customers a month to the lending team after spotting mortgage or auto loan interest during routine conversations.
Skills
- Underwriting basics: DTI and LTV calculation, credit report review, Fannie Mae guideline checklists
- Systems: Desktop Underwriter (DU), Encompass (exposure), Excel
- Finance fundamentals: Financial statement reading, risk terminology, loan documentation
Senior underwriter resume example
A senior underwriter eleven years in, now managing a team across residential and commercial lending. The bullets move from reviewing individual files to setting guidelines, cutting portfolio-wide risk and mentoring underwriters, and the summary names the team size and portfolio value.
Senior example resume · fictional person
Summary
Senior underwriter with 11 years across residential and commercial lending, leading a team of 6 underwriters at a regional bank. Owns underwriting guidelines for a $400M loan portfolio, cut the team's average file turnaround from 5 days to 2, and built the fraud-detection checklist now used bank-wide.
Experience
Senior Underwriter / Team Lead, Larkspur Financial
Denver, CO · May 2021 – Present
- Lead a team of 6 underwriters reviewing conventional, FHA, VA and small-commercial files across a $400M portfolio.
- Rewrote internal underwriting guidelines to close 5 gaps flagged in the prior year's audit, passing the next regulatory exam with zero findings.
- Cut the team's average file turnaround from 5 days to 2 by restructuring the exception-review queue and adding a same-day triage step.
- Built a fraud-detection checklist after catching a pattern of falsified pay stubs across 14 files from 2 brokers; the checklist is now used bank-wide.
- Mentor and train 6 underwriters on commercial financial statement analysis, cutting new hires' average ramp time from 6 months to 3.
Underwriter, Trailmark Credit Union
Denver, CO · Jul 2017 – Apr 2021
- Underwrote 20-25 residential loan files a week, maintaining a 90-day delinquency rate of 1.1% against a peer average of 2.4%.
- Introduced a self-employed income worksheet adopted by 10 underwriters, cutting that file type's average review time by 40%.
- Partnered with compliance to resolve 3 years of recurring audit findings on exception documentation, reducing findings to zero.
Underwriter, Coppertree Bank
Denver, CO · Aug 2014 – Jun 2017
- Reviewed 15-18 conventional and FHA loan files a week against Fannie Mae and HUD guidelines.
- Verified employment and re-pulled credit on files near closing, catching 20 cases of new undisclosed debt over 3 years.
Skills
- Underwriting: Residential and small-commercial loans, DTI/LTV analysis, financial statement review, fraud detection
- Systems: Encompass, Desktop Underwriter (DU), Loan Prospector (LP)
- Leadership: Team management, guideline authoring, audit and compliance partnership, mentoring
Certifications
- NAMU Certified Mortgage Underwriter (CMU), 2018
Education
- B.S. Business Administration, University of Colorado Denver, 2014
How to write an underwriter resume
Five steps, in the order a recruiter reads the page. The format around them stays plain for every job: one column, standard headings, newest role first.
Header: name, target title and links
Use the title “Underwriter” and specify the type (mortgage, commercial, insurance) in your headline, since guidelines, systems and metrics differ enough that hiring managers filter by specialty.
Summary: what you do and your best proof
Name your loan or policy type, your file volume, and one result that shows decision quality, such as a delinquency or audit outcome. Skip lines like “detail-oriented team player”; a specific risk metric proves it better.
Experience: newest first, a result in every bullet
Open each bullet with the file type and volume, then the decision and its result: a risk caught, a turnaround improved or an exception resolved. A count of files reviewed says little; a delinquency rate below average says a lot.
Skills: grouped, in the ad's words
Group into underwriting knowledge, systems (Encompass, DU, LP) and guideline sets (Fannie Mae, FHA, VA). Name the specific systems and guidelines you know rather than writing “underwriting software.”
Education and certifications
List your degree and the year, plus a certification such as NAMU's CMU or a relevant insurance designation if you hold one. Without underwriting experience, highlight a loan processing or financial analysis role that shows the same close reading of documents.
Skills to put on an underwriter resume
Hard skills are the tools and methods of the job; soft skills are how you work with people. Each comes with one way to prove it, because a skill named only in a list counts for little. Add the ones you really have.
Hard skills
- DTI and LTV analysis
- Mention the loan type and give an example ratio range you commonly approve against.
- Fannie Mae / Freddie Mac guidelines
- Name the specific guideline set and a decision you made by applying it.
- FHA/HUD guidelines
- Mention FHA-specific documentation, like mortgage insurance rules, you apply regularly.
- Desktop Underwriter (DU)
- Say how many files a week you run through it and how you resolve DU findings.
- Encompass
- Mention a workflow or report you built or used in Encompass to speed up file review.
- Self-employed income review
- Name the documents you read (tax returns, P&L) and a file count where it mattered.
- Credit report analysis
- Describe a red flag you caught through credit review, with its outcome.
- Financial statement analysis
- For commercial underwriting, name the statement types and the loan size they informed.
- Fraud detection
- Describe a specific fraud pattern you caught and the number of files or dollars involved.
- QM/ATR compliance
- Mention an audit result or exception rate that shows your files meet the rule.
- Exception documentation
- Give the number of exception files you handle and your approval turnaround.
- Risk portfolio management
- If senior, name the portfolio size you oversee and a risk metric you improved.
Soft skills
- Judgment under pressure
- Describe a volume or deadline you met while holding your decision quality steady.
- Attention to detail
- Mention a specific error or inconsistency you caught before a file closed.
- Clear decision documentation
- Describe how you write up a denial or exception so it holds up in an audit.
- Collaboration with loan officers or brokers
- Give the number of officers or brokers you work with regularly and a result of that collaboration.
- Consistency
- Mention an audit or QC result showing your decisions matched guidelines reliably.
- Mentoring
- Count the underwriters or processors you have trained and a result, like reduced error rate.
- Adaptability to guideline changes
- Describe a guideline update you implemented and how quickly your team adapted.
Underwriter resume bullet examples: weak vs strong
The same work, written two ways. The strong version names the tool, the scope and a result; the numbers are examples, yours must be real.
Weak: Underwrote loan files.
Strong: Underwrote 22 commercial loan files a week averaging $650,000, with a charge-off rate of 0.8% against a portfolio average of 1.9%.
Volume, dollar size and a risk result in one line.
Weak: Reviewed applications for risk.
Strong: Caught a pattern of inflated rental income across 9 files from one broker, flagging the broker for review before any funded.
A specific risk caught, with a number and an outcome.
Weak: Ensured compliance with guidelines.
Strong: Audited 150 of my own closed files against QM/ATR rules and found zero compliance exceptions over 2 years.
Turns a vague compliance claim into a verifiable track record.
Weak: Worked with loan officers to resolve issues.
Strong: Cleared stuck conditions on 30 files a quarter by meeting weekly with 5 loan officers, cutting average time-to-close by 4 days.
Shows collaboration with a frequency and a measurable result.
Weak: Analyzed financial documents.
Strong: Read 3 years of tax returns and P&L statements for self-employed borrowers, qualifying income correctly on 40 files that an automated tool had flagged as unclear.
Specific document types and the value added beyond automation.
Weak: Approved or denied loans.
Strong: Denied 15 files for undisclosed liabilities found through re-pulled credit reports, preventing an estimated $4M in exposure.
A decision measured by the risk it avoided.
15 more underwriter resume bullet examples
Grouped by area of the job, so you can find the ones closest to your work. Keep the shape (action, scope, result) and replace the invented numbers with your own.
File volume and decision quality
- Underwrote an average of 24 residential loan files a week at an average loan size of $310,000, with a 90-day delinquency rate of 1.3%.
- Maintained a file return rate under 5% over 2 years by double-checking income calculations against source documents before submission.
- Cleared a backlog of 45 pending files in one month by prioritizing by closing date, without missing any committed closing dates.
Risk and fraud detection
- Identified a pattern of inflated self-employment income across 11 files tied to one tax preparer, leading to a bank-wide review of that preparer's clients.
- Caught 9 cases of undisclosed new debt through credit re-pulls within 48 hours of closing, preventing likely early payment default.
- Flagged a forged employment verification letter that led to the referral of a broker relationship for compliance review.
Process improvement
- Streamlined the exception-approval checklist, cutting average exception file turnaround from 3 days to 1.
- Built an Excel tracker for file status across 4 underwriters, cutting status-update emails to loan officers by half.
- Proposed a change to the self-employed income worksheet that cut average review time on those files by 35%.
Compliance and audit
- Passed 3 consecutive annual regulatory audits with zero underwriting exceptions on a sample of 50 files each year.
- Rewrote exception documentation templates after an audit flagged unclear reasoning, eliminating that finding in the next review.
- Reviewed 200 jumbo loan files over 18 months with zero post-close repurchase requests.
Collaboration and mentoring
- Trained 5 new underwriters on reading self-employed income documentation, cutting their average ramp time by 2 months.
- Met weekly with 6 loan officers to clear stuck conditions, reducing average file time-to-close by 3 days across the team.
- Ran a monthly credit-policy huddle for 8 loan processors, cutting files returned for missing documents from about 20 a week to 9.
Underwriter resume summary examples
Two or three lines on what you do and your strongest proof. Start from the one closest to your level and use your own facts.
Entry-level underwriter with a finance degree and a loan processing internship at a regional bank, reviewing conventional loan files under a senior underwriter's guidance. Comfortable with Desktop Underwriter and reading credit reports and income documentation.
Underwriter with 6 years in residential mortgage lending, reviewing conventional, FHA and VA files with a delinquency rate below branch average. Redesigned the exception-approval process to cut average turnaround from 4 days to 36 hours.
Senior underwriter with 11 years across residential and commercial lending, now leading a team of 6 underwriters. Owns the underwriting guidelines for a $400M loan portfolio and cut the team's average file turnaround from 5 days to 2.
Common underwriter resume mistakes
Each one is easy to make and quick to fix before you apply.
Counting files instead of showing decision quality
“Reviewed 500 loan files” doesn't say whether those decisions held up. Add a delinquency, repurchase or audit result next to your volume.
No guideline set named
Listing “underwriting” alone hides which rules you know. Name Fannie Mae, FHA, VA or the relevant commercial or insurance standard.
Omitting the loan origination system used
Many postings require specific experience with Encompass, DU or LP. List the systems you have used, not just “loan software.”
Framing denials only as negative outcomes
A well-documented denial that avoided risk is a strength. Describe what the denial protected against, with a number if you have one.
Hiding fraud or risk catches in vague language
“Identified risk factors” tells a reader nothing concrete. Name the specific red flag, how many files it touched and what happened next.
ATS tips for an underwriter resume
Applicant tracking systems turn your file into text that recruiters search, mostly for the skills and titles in the ad. They rarely reject a resume on their own; one that parses badly or misses the ad's words just doesn't come up.
- State your loan or policy type (conventional, FHA, VA, commercial) and the guideline set you underwrite against (Fannie Mae, FHA/HUD).
- Give your weekly or monthly file volume and average dollar size; underwriting ads often screen for both.
- Show your decision quality with a number: delinquency rate, repurchase rate, denial rate or audit result.
- Name the loan origination system you used (Encompass, DU, LP); many postings require experience with a specific one.
- If you caught fraud or risk other reviewers missed, describe the red flag and what it prevented.
For the format itself, run the free ATS resume checklist.
Everything for Underwriters
- Underwriter cover letter examplesThree example letters and a short email version
- Underwriter interview questions30 questions with sample answers
- Underwriter job descriptionDuties, skills and requirements
- How to tailor your resume without lying
Other resume examples
Underwriter resume FAQ
What skills do I need to become an underwriter with no experience?
A finance, accounting or business background helps, along with comfort reading tax returns and credit reports. Many lenders hire loan processors or junior underwriters first and train on guidelines and systems like Desktop Underwriter.
Should I mention my approval or denial rate on an underwriter resume?
Only if you can frame it as a sign of sound judgment, such as a low delinquency or repurchase rate on files you approved, rather than just a raw count of approvals.
Do I need a certification to list on an underwriter resume?
It's not required, but a credential such as NAMU's Certified Mortgage Underwriter or an insurance CPCU designation signals depth and can help with ATS keyword matches.
How is a mortgage underwriter resume different from a commercial or insurance underwriter resume?
The core structure is the same, but swap in the relevant guidelines, systems and risk metrics: Fannie Mae and DU for mortgage, financial statement analysis for commercial, loss ratios for insurance.
How we built this page
The FindAJobAI team wrote the three example resumes, the bullets, the skills and the advice for underwriter roles. The people, employers and numbers in the examples are invented; the structure, the tools and the way each bullet is built are the parts to copy.
Once we track enough live underwriter job ads, this page also shows the skills they ask for most, counted the same way as our in-demand skills report.
Last reviewed on November 1, 2026.